Filing a water or mold claim in Florida can be confusing, and the quality of your documentation often shapes how smoothly it goes. A restoration company cannot decide your coverage, but it can document the loss thoroughly and communicate factually with your carrier so your claim rests on organized evidence.
Claim support means creating a clear record from the first hour: photos, moisture readings, equipment logs, a room-by-room inventory, and a scope that separates emergency mitigation from repairs. It also means being honest about what insurance does and does not cover.
Ultra Mold Water Restoration helps Miami-Dade homeowners and businesses document water and mold losses and coordinate with adjusters, while being clear that the carrier makes the coverage decision.
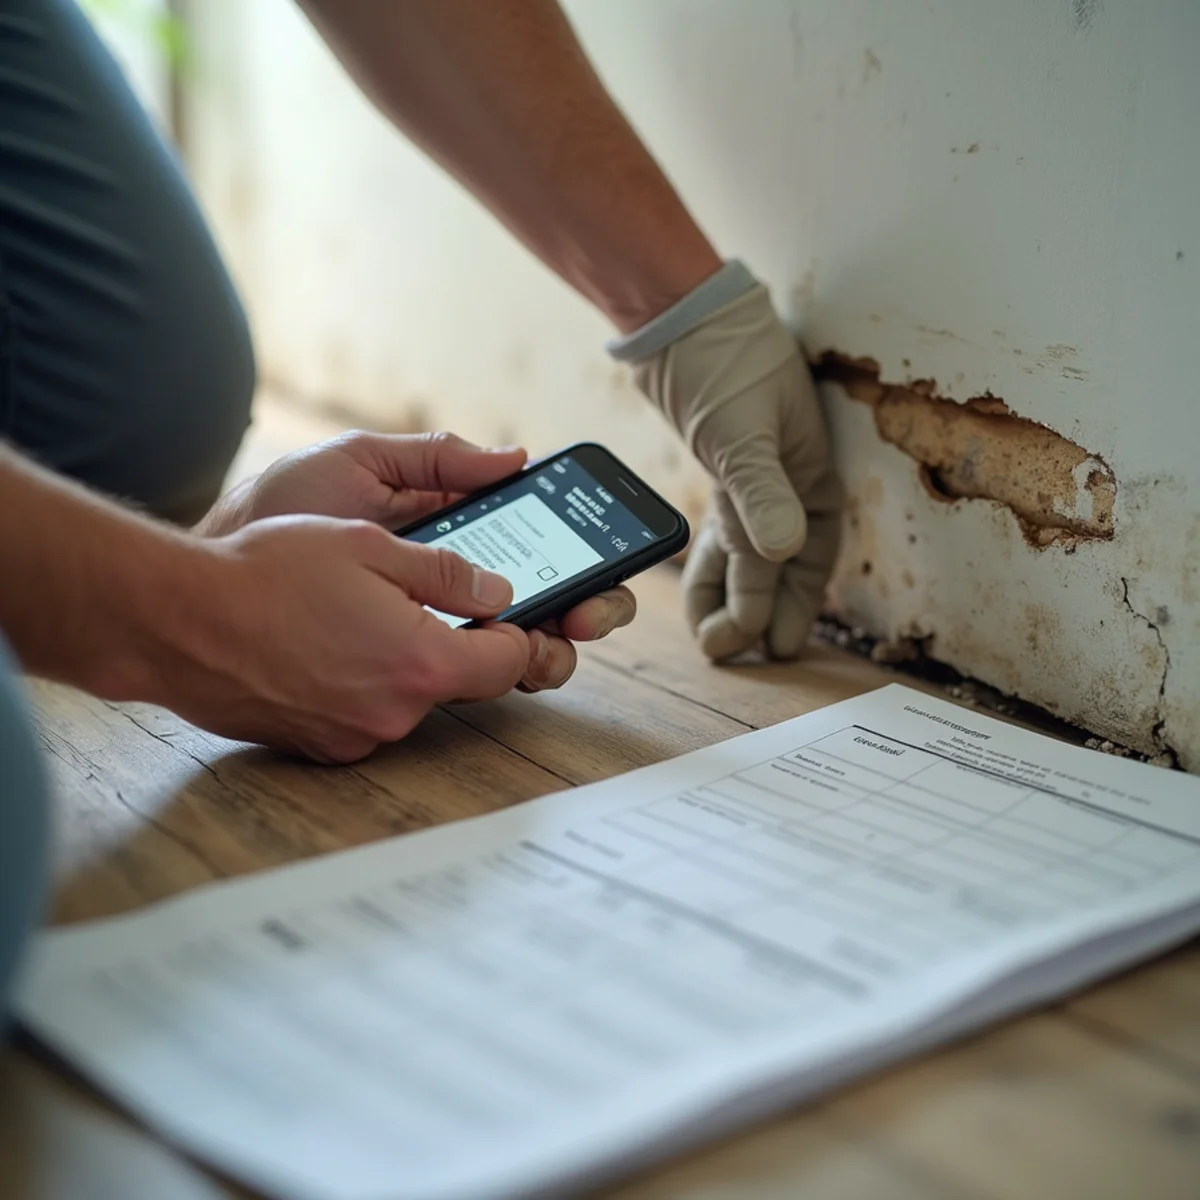
What We Can and Cannot Do
Here is the honest version, because it protects you. A restoration company can document damage, take moisture readings, log equipment, build a room-by-room inventory, provide a written scope, and communicate factually with your insurer. What a restoration company cannot do is decide coverage or promise a payout; the carrier makes that call based on your policy.
We never describe damage as covered until the carrier confirms it in writing. Being straight about that up front is part of doing right by our neighbors, and it keeps your claim on solid ground.
Coverage in Florida Is Not Automatic
Do not assume every water loss is covered, or that it falls under the same coverage. Sudden interior plumbing failures, roof events, stormwater, surge, groundwater, and sewer backups can be treated very differently based on the policy, endorsements, exclusions, deductible, cause, and facts of the loss.
Importantly, homeowners insurance does not automatically cover flood or stormwater damage; flood coverage is typically separate, and sewer-backup coverage is often its own endorsement. Knowing which coverage may apply to your specific event helps set realistic expectations.
How We Support Your Claim
- 1
Document from the first hour
We photograph every affected room, the source, and the water line, and we begin moisture readings and equipment logs immediately so the record is complete.
- 2
Prompt, safe mitigation
We begin the emergency mitigation most policies expect, which also demonstrates that reasonable steps were taken to prevent further damage.
- 3
Room-by-room inventory
We help build a damage inventory and note items moved, discarded, or opened for safety, photographing contents before disposal when possible.
- 4
Clear, itemized scope
We provide a scope that separates mitigation, repair, contents, permits, and deductible so you and your adjuster can review it line by line.
- 5
Factual carrier communication
We coordinate with your adjuster using facts and documentation, without promising coverage, and keep records of the communication.
What to Document for Your Claim
Good documentation is the homeowner's best tool. The more organized your record, the easier the conversation with your carrier.
- Photograph every room, damaged item, label, serial number, and water line
- Record the discovery time, shutoff time, and call time
- Notify the insurer promptly and request the claim number and adjuster contact
- Keep receipts, estimates, moisture readings, equipment logs, and invoices in one folder
- Photograph contents before discarding them unless safety requires immediate disposal
- Keep communication factual and avoid describing damage as covered until confirmed
An Honest Partner Through the Process
As a family-owned local company, our reputation depends on doing this the right way. We give you organized documentation, an itemized scope, and straight answers, and we tell you when a loss may not be covered rather than setting up a disappointment later.
If your carrier disputes part of the scope, we can explain and support the documentation behind our work. The decision remains the carrier's, but you will have a clear, defensible record on your side.
Why Choose Ultra Mold for Claim Support
Documentation is where claims are won or lost, and it has to start in the first hour. We build that record as we mitigate, then communicate with your adjuster factually, without ever promising coverage we cannot control. Straight answers up front are how a family-owned local company earns repeat neighbors. That honesty is also practical: a carrier is far more likely to move quickly on a claim backed by clean, consistent, well-organized documentation.
- First-hour photos, moisture readings, and equipment logs
- An itemized scope that separates mitigation, repair, and contents
- Factual coordination with your adjuster, no coverage promises
- Prompt mitigation that shows reasonable steps were taken
- A defensible record if the carrier disputes part of the scope
Claim Support Across Miami-Dade and Broward
We document and support water and mold claims for homeowners and businesses throughout the region, including Kendall, Coral Gables, and Hialeah in Miami-Dade, and Pembroke Pines, Miramar, and Davie in Broward.
Florida water claims turn on the cause and the policy language, and those vary widely across South Florida properties: older homes with plumbing history, coastal condos with wind and flood exposure, and newer builds with different endorsements. We tailor the documentation to your specific loss and carrier rather than filing a one-size record.
We also make a point of setting realistic expectations early. Not every water loss is covered, and different causes, sudden plumbing failures, roof events, stormwater, surge, groundwater, and sewer backups, can be treated very differently under the same policy. Rather than tell you what you hope to hear, we explain which coverage may apply to your specific event, document the loss so the facts are clear, and let the carrier make its decision on an organized record. When a scope is disputed, that thorough documentation is what gives you a defensible basis for the conversation.
What affects the cost
Every loss is different. These are the factors that shape your estimate — we confirm the scope during your free inspection, and the figures below are planning ranges, not a quote.
- Scope and severity of the underlying water or mold loss
- Extent of documentation and inventory required
- Whether the loss involves multiple coverages or disputes
- Coordination time with adjusters and other parties
- Deductible, endorsements, and policy specifics that affect the claim
- Restoration costs follow standard planning ranges; what your policy pays is determined by the carrier
Need help right now?
Certified crews, 24/7, across South Florida.
Frequently asked questions
We do not file or decide the claim, but we support it by documenting the loss thoroughly, providing an itemized scope, and coordinating factually with your adjuster. You file with your carrier, and the carrier decides coverage.
Sometimes, depending on the cause and policy. Sudden plumbing failures and certain roof events may be covered, but flood and stormwater are not automatically covered and often require separate flood coverage. Coverage depends on your policy, exclusions, deductible, and the facts of the loss.
Photos of every affected room and item, the water line and source, dates for discovery and shutoff, a room-by-room inventory, and receipts, estimates, moisture readings, and invoices. Keep contents photographed before disposal unless safety requires otherwise.
We can explain and support the documentation behind our scope and readings. The carrier makes the final coverage decision, but a clear, organized record gives you a defensible basis for the conversation.
Yes. We coordinate with your adjuster using photos, moisture readings, equipment logs, and an itemized scope, and we keep records of that communication. We present facts and documentation; we do not describe damage as covered, because the carrier makes the coverage decision.