Coverage Comes Down to One Question: What Caused It?
The most common question we hear in Broward and across South Florida is whether insurance will pay. The honest answer is that it depends almost entirely on the cause of the damage and the specific language in your policy. Two homes with identical-looking water stains can get opposite coverage decisions because one leak was sudden and the other developed slowly. Understanding that distinction before you file puts you in a far stronger position.
This guide explains the general rules, but it is not a substitute for reading your own declarations page. Your carrier makes the final coverage determination, and policies vary widely, especially in Florida's insurance market.
Florida's property insurance landscape has shifted a great deal in recent years, with carriers tightening terms, adjusting exclusions, and changing how they handle water and mold claims. A policy you bought several years ago may read very differently from a renewal quote today. That makes it worth reviewing your coverage annually rather than assuming it is unchanged, because the details that decide a claim, the mold sublimit, the deductible, the flood exclusion, are exactly the ones that tend to move.
Sudden and Accidental vs. Gradual Damage
The dividing line in most homeowners policies is whether the damage was sudden and accidental or gradual. A pipe that bursts without warning is the classic covered event. A pipe that dripped behind a cabinet for months, causing rot and mold, is often excluded as a maintenance issue the homeowner should have caught. This is why documentation and speed matter so much. When you report promptly and can show the loss was sudden, our insurance claims support helps present the evidence in the terms adjusters use.
Flood Is a Separate Policy Entirely
This is the single most misunderstood point in South Florida. Standard homeowners insurance does not cover flood, defined as rising surface water from storms, canals, or tidal events. Flood coverage requires a separate policy, typically through the NFIP or a private flood insurer. Given that our rainy season runs May through October with normal rainfall near 45 inches, and that king tides and storm surge reach inland neighborhoods, going without flood coverage is a real gamble here. If floodwater enters your home, our flood cleanup crews can still restore it, but whether your homeowners policy pays is a different matter from whether the work gets done. Residents throughout Broward County should confirm they carry flood coverage in addition to their standard policy.
How Mold Coverage Usually Works
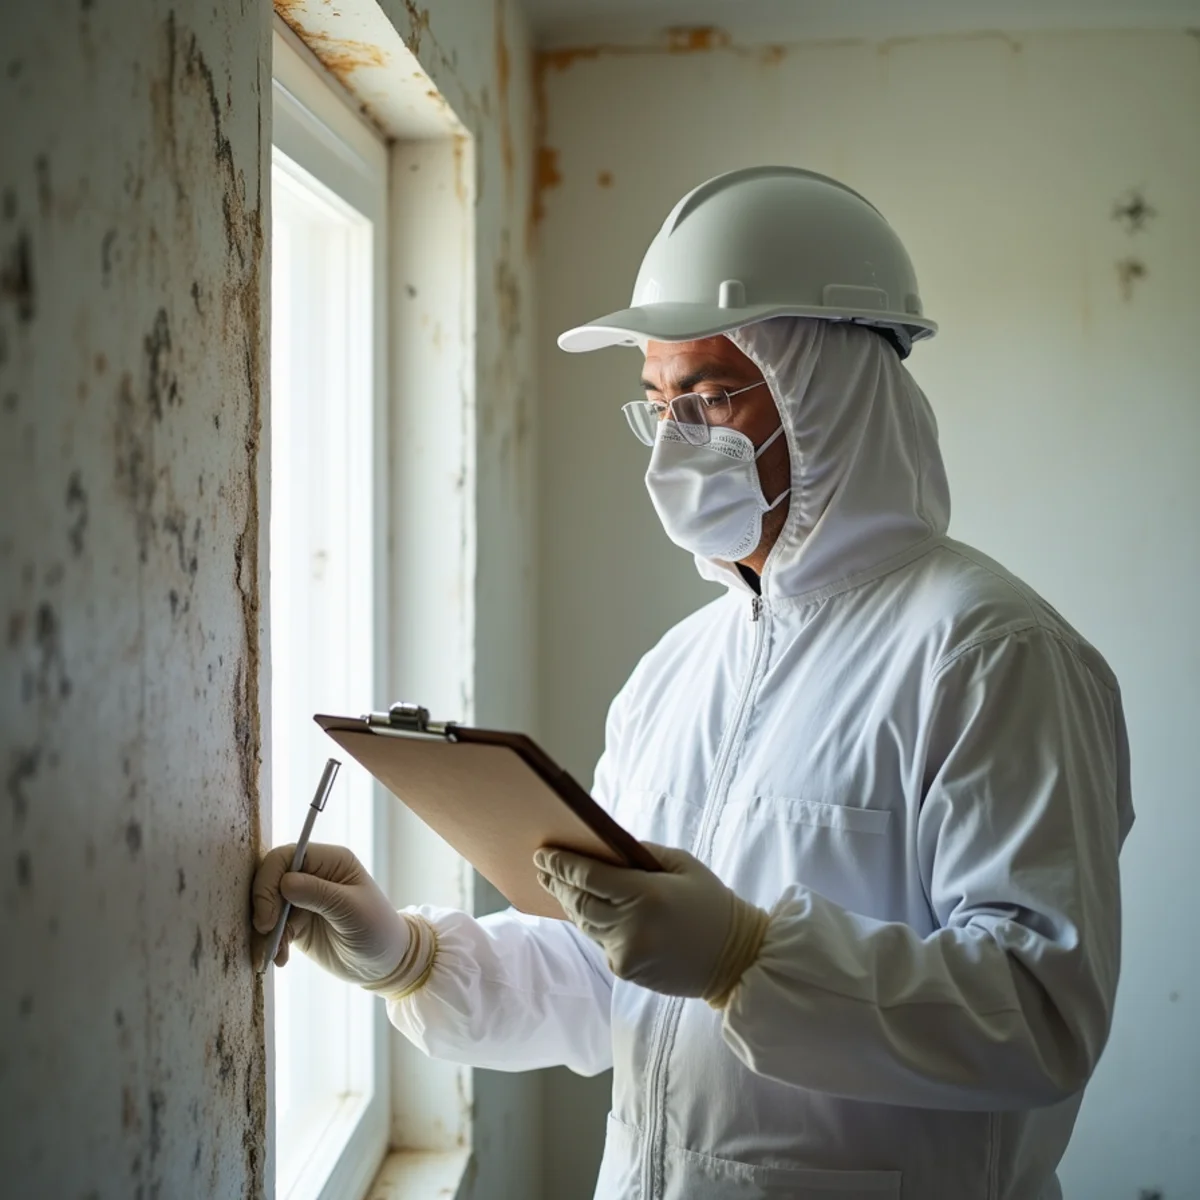
Mold coverage is often conditional. Many Florida policies cover mold only when it results directly from a covered water event, and even then they frequently cap the payout, sometimes at a few thousand dollars. Mold caused by a long-term leak, high humidity, or deferred maintenance is commonly excluded outright. Because Florida requires mold remediators to be licensed and to carry at least $1 million in general liability, using a properly licensed company also protects your claim; insurers scrutinize unlicensed work. Our licensed mold remediation team documents the moisture source alongside the mold, which is exactly the connection an adjuster needs to approve coverage.
The practical takeaway is that the chain of cause and effect decides everything. If you can show that a sudden, covered water event led directly to the mold within a short window, you are in the strongest position. If months passed between the leak and the discovery, the carrier may argue the damage was gradual and therefore excluded. This is one more reason to report and document promptly rather than waiting to see whether a small problem gets worse; the paper trail you create early is often what separates a paid mold claim from a denied one.
The Fine Print That Trips People Up
- Mold sublimits: your policy may cover water damage generously but cap mold at a low separate limit.
- Anti-concurrent causation clauses: if excluded flood and covered wind both contribute, the exclusion can control the outcome.
- Proof-of-loss deadlines: Florida policies impose time limits on reporting and documenting a claim.
- Wear-and-tear exclusions: gradual deterioration is almost never covered, even if it ends in a sudden failure.
- Named-peril vs. open-peril: what is covered differs sharply between policy types.
What to Do Before and After a Loss
Before anything happens, read your policy and confirm whether you carry flood coverage and what your mold sublimit is. After a loss, document everything before cleanup, report promptly, and keep the damaged materials available for the adjuster when possible. Do not let water sit while you wait for an answer on coverage; delaying drying can worsen the damage and give the carrier grounds to argue you failed to mitigate.
Ultra Mold Water Restoration works with homeowners and their insurers every day, and we are available 24/7 across South Florida. If you are facing water or mold damage and are unsure about coverage, call (866) 688-0301 and we will document the loss properly from the start.
Dealing with this right now?
Ultra Mold responds 24/7 across South Florida.
Frequently asked questions
No. Standard homeowners insurance excludes flood, which is rising surface water. You need a separate NFIP or private flood policy, which is strongly advised in South Florida given the rainy season and coastal flooding.
Often only when it results from a covered water event, and frequently with a dollar cap. Mold from long-term leaks, humidity, or neglect is commonly excluded. Your carrier decides based on the cause and your policy language.
Florida requires mold remediators to be licensed and carry at least $1 million in liability coverage. Insurers scrutinize unlicensed work, so using a licensed company helps protect your claim and your home.
Document the damage before cleanup, report the loss promptly, and begin mitigation quickly to prevent it from worsening. A licensed restoration company can capture the moisture and source evidence adjusters look for.